What is the market overview of the Classification File Folder Market?
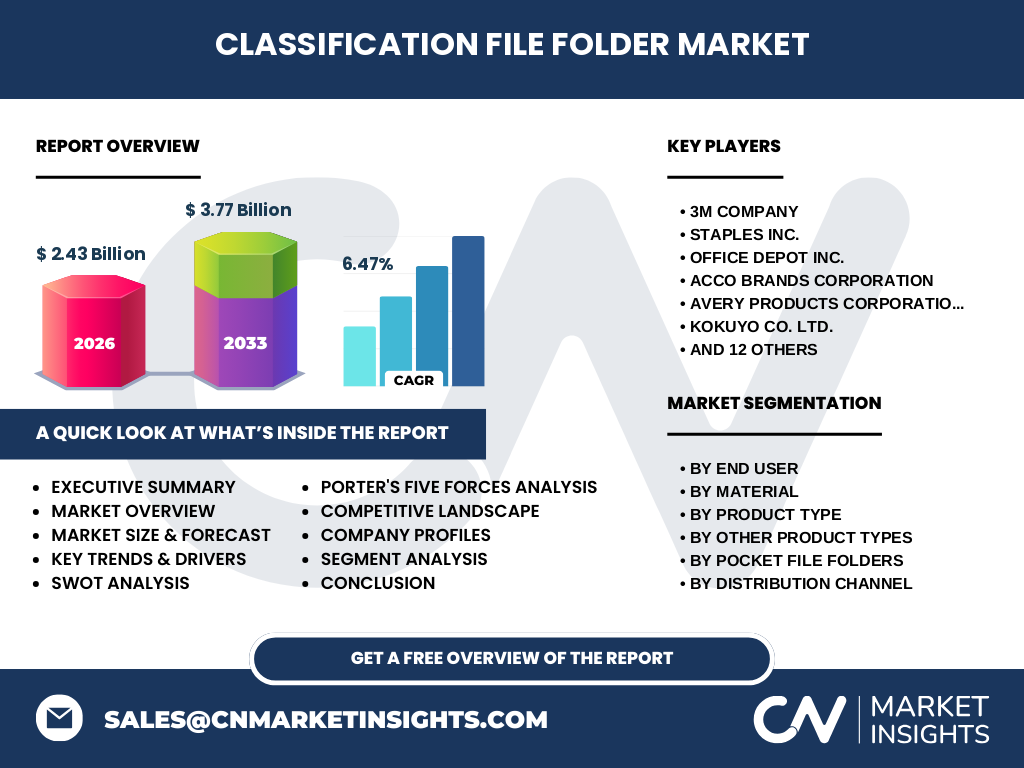
Our analysis indicates that the Classification File Folder Market reached a valuation of $2.43 Billion in 2026, driven by critical physical document management needs in legal, medical, and corporate sectors. Essential raw materials like virgin craft paper, recycled pulp, and polypropylene polymers dictate supply chain economics, while compliance frameworks such as HIPAA and GDPR mandate secure paper retention alongside digital workflows.
Key market drivers, restraints, challenges, and opportunities shaping the Classification File Folder Market
Growth is propelled by rigorous archival regulations in legal and healthcare environments requiring durable Pressboard and Expanding File Folders. Conversely, enterprise digitization acts as a primary restraint. However, the opportunity lies in eco-friendly innovations like Eco Friendly Hanging File Folders and recycled material lines, which help manufacturers navigate tightening municipal sustainability directives and volatile pulp commodity prices.
Emerging trends and growth patterns in the Classification File Folder Market
The shift toward color-coded and modular organization systems is transforming workplace productivity. Color Coded Hanging File Folders and Gusseted Expanding File Folders are gaining traction in high-volume administrative centers. Furthermore, corporate ESG mandates are accelerating demand for biodegradable plastic rails and post-consumer recycled paper substrates across all major distribution networks.
COVID-19 impact analysis and recovery trajectory for the Classification File Folder Market
The pandemic severely disrupted the industry as remote work mandates shuttered corporate offices, educational institutions, and government agencies, drastically reducing demand for bulk Suspension File Folders. The recovery trajectory has been shaped by hybrid office models, where decentralized administrative hubs require localized filing solutions, prompting suppliers to optimize e-commerce logistics through platforms like Amazon and direct-to-enterprise channels.
Competitive landscape and strategic dynamics in the Classification File Folder Market
The market exhibits a moderately consolidated structure featuring heavyweights like ACCO Brands Corporation, 3M Company, and Smead Manufacturing Company. Strategic dynamics center on product diversification, encompassing everything from heavy-duty metal rod suspension files to custom-printed presentation folders. Industry leaders leverage extensive distribution networks spanning big-box stationery stores and specialized B2B office suppliers to maintain pricing power.
Executive summary of key findings within the Classification File Folder Market
Our comprehensive report reveals a robust market trajectory, projecting the sector to expand from $2.43 Billion in 2026 to $3.77 Billion by 2033 at a steady 6.47% CAGR. Key value pools concentrate within legal firms and healthcare facilities utilizing durable multi-pocket and heavy-duty suspension designs, signaling sustained demand despite broad enterprise software adoption.
Market forecast: projected growth trajectory from 2027 to 2033
Based on our research, the market is poised for accelerated expansion, scaling from its 2026 baseline to reach $3.77 Billion by 2033, registering a compound annual growth rate of 6.47%. This growth is underpinned by rising infrastructural investments in emerging economies and the continuous replacement cycle of physical archival systems across government and judicial bodies.
Segmentation analysis across product types, materials, and end-users
The market segments intricately across End User (Corporate Offices, Government Agencies, Educational Institutions, Healthcare Facilities, Legal Firms, Banking Institutions), Material (Paper, Plastic, Cardboard), and Product Type (Hanging, Expanding, Pocket, and Suspension File Folders). Each segment addresses specialized workflows, from legal ledger management to secure banking document archiving.
Regional market analysis and geographic performance distribution
Geographic performance reflects varying administrative densities and regulatory compliance standards across continents. North America and Europe dominate consumption due to stringent legal and healthcare record-keeping mandates, while Asia-Pacific emerges as the fastest-growing region, propelled by rapid commercial office expansion and burgeoning manufacturing hubs requiring structured corporate filing systems.
In-depth regional review of key geographic markets
North America remains a mature stronghold supported by established corporate legal frameworks, whereas the Asia-Pacific region benefits from lower manufacturing overheads and expanding white-collar employment in urban centers. European markets prioritize stringent environmental certifications, driving high adoption rates for recycled paper and biodegradable plastic rail file folders over traditional synthetic alternatives.
Company profiles and strategic positioning of leading industry players
Industry leaders like Kokuyo Co. Ltd., Deli Group, and Exacompta Clairefontaine SA leverage regional manufacturing efficiencies and localized distribution agreements. Meanwhile, US-based giants such as Fellowes Brands and TOPS Products LLC focus on ergonomic design innovations and heavy-duty archival solutions tailored to enterprise compliance requirements.
Porter's Five Forces analysis of the Classification File Folder Market
Bargaining power of suppliers remains moderate due to fluctuations in pulp and polymer costs. Threat of substitutes is mitigated by the legal necessity of physical paper archiving. However, competitive rivalry is intense among established stationery conglomerates, compelling continuous innovation in eco-friendly substrates and durable fastening mechanisms.
SWOT analysis of the global industry ecosystem
Key strengths include high product durability and established B2B distribution channels. Weaknesses involve vulnerability to digital substitution and raw material cost inflation. Opportunities lie in emerging market office expansion and sustainable product lines, while threats stem from strict environmental regulations on plastic manufacturing and recycled material supply chain bottlenecks.
Value chain analysis from raw material extraction to end-user delivery
The value chain initiates with timber harvesting, chemical pulp processing, and petrochemical extraction for plastic components. Converters and manufacturers mold these raw inputs into finished hanging, expanding, or pocket folders. Distribution flows through wholesale B2B suppliers, hypermarkets, and specialized online stores before reaching corporate, legal, and educational end-users.
Investment insights and high-potential growth areas
Strategic investors should target manufacturers scaling production of Eco Friendly Hanging File Folders and recycled material variants. High-margin opportunities exist in custom-printed and reinforced-edge pocket folders catering to specialized legal and medical compliance applications where document integrity is paramount.
Conclusion and core strategic takeaways for stakeholders
The data confirms that physical document organization remains resilient, with the market expanding to $3.77 Billion by 2033 at a 6.47% CAGR. Stakeholders must pivot toward sustainable manufacturing processes and leverage e-commerce distribution channels to capture shifting B2B procurement preferences in hybrid work environments.
Research methodology detailing data triangulation and analytical modeling
Our baseline estimates are rigorously triangulated by combining global trade registry data, primary stakeholder interviews with procurement executives across office supply chains, and secondary macroeconomic indicators. econometric modeling reconciles production output volumes with regional end-user consumption metrics to ensure high forecast accuracy.
Scope of the report, coverage parameters, and operational limitations
This report encompasses global market evaluations for classification file folders from 2026 through 2033, analyzing segmentation across materials, product sub-types, and distribution channels. Limitations include unpredictable fluctuations in raw pulp commodity pricing and localized trade policy shifts that may impact cross-border manufacturing logistics.
Recent developments, strategic partnerships, and product launches
Recent industry moves highlight a strong push toward circular economy practices, with major players such as ACCO Brands and Smead introducing closed-loop recycling programs. Partnerships between stationery manufacturers and e-commerce platforms have also streamlined direct-to-office supply chains, optimizing inventory replenishment for corporate clients.